Mortgages by TIFF · Licensed in Ontario & Alberta
Take the pressure off every single month.
We help Canadian homeowners refinance, consolidate high-interest debt and use their home equity to lower what goes out every month — with the trade-offs shown honestly.
- Mortgage volume completed
- $146M+
- Mortgage volume completed
- Credit check to start
- $0
- Credit check to start
- Personal reply to every inquiry
- 1 day
- Personal reply to every inquiry
Led by
Tiffany Quaye
Licensed Mortgage Agent · Pineapple Financial Inc.
Six ways your mortgage can work harder.
Most homeowners carry more monthly pressure than they need to. We compare banks, alternative and private lenders to restructure what you owe around what you can actually afford.
- 01
Mortgage Refinancing
Restructure your mortgage around the life you have now — amortization, term and payment — and free up room in the monthly budget.
Learn more - 02
Debt Consolidation
Roll credit cards, lines of credit and car loans into one mortgage payment at a mortgage rate, instead of several payments at 18% or more.
Learn more - 03
HELOC & Home Equity
Turn the equity you've built into a flexible line of credit for renovations, debt payoff or a safety net — pay interest only on what you use.
Learn more - 04
Mortgage Renewals
Your lender's renewal letter is rarely the best offer. We compare renewing, switching and refinancing before you sign anything.
Learn more - 05
Second Mortgages & Private Lending
When the bank says no, alternative and private lenders can still say yes — with a clear exit plan back to a regular mortgage.
Learn more - 06
Self-Employed Mortgages
Business owners, contractors and commission earners. We find lenders who understand your income instead of penalising it.
Learn more
Four steps, and you can stop at any one.
- 1
Free review
Tell us your mortgage, your balances and what's stressing you out. No credit check at this stage.
- 2
We shop the lenders
Banks, credit unions, alternative and private lenders — compared on one application, not just on rate.
- 3
Your numbers, side by side
The monthly change, the total interest and the cost to get there. Including when waiting is the better call.
- 4
Start keeping more
We handle the lender, documents, appraisal and lawyer. You start feeling the difference every month.
How much could come off each month?
Pick your situation and enter a few numbers. You'll see the monthly difference right away. It's an illustration, not an approval.
See what consolidating your high-interest debt could look like.
Enter 4 numbers. We compare your current mortgage + minimum debt payments against one simpler mortgage payment at 5% over 30 years.
Fixed for this scenario
- 5%
- New mortgage rate
- 30 yrs
- Amortization
- 18%
- Rate on unsecured debt
Monthly Impact
Assumptions
- New mortgage priced at 5% over a 30-year amortization, monthly, semi-annual compounding.
- Unsecured debt carries 18% interest with a 3% minimum monthly payment.
- Refinancing capped at 80% of your estimated home value.
- Penalties, legal, appraisal and discharge costs are not included.
This is an illustration, not a mortgage approval or financial recommendation. Actual results depend on interest rates, penalties, lender guidelines, qualification and your full financial situation.
Homeowners carrying more monthly pressure than they should be
Most of our clients own their home, have built real equity, and are servicing debt that was never designed to be carried this long.
Payments feel tight
Credit cards, a line of credit and a car loan are eating the room in your budget every month.
Equity is sitting still
Your home has gone up in value and you'd like that equity doing something useful.
Renewal is coming
You've been offered a renewal rate and want to know whether signing it is the right move.
Your file isn't simple
Self-employed, commission income, or credit that took a hit. Options still exist.
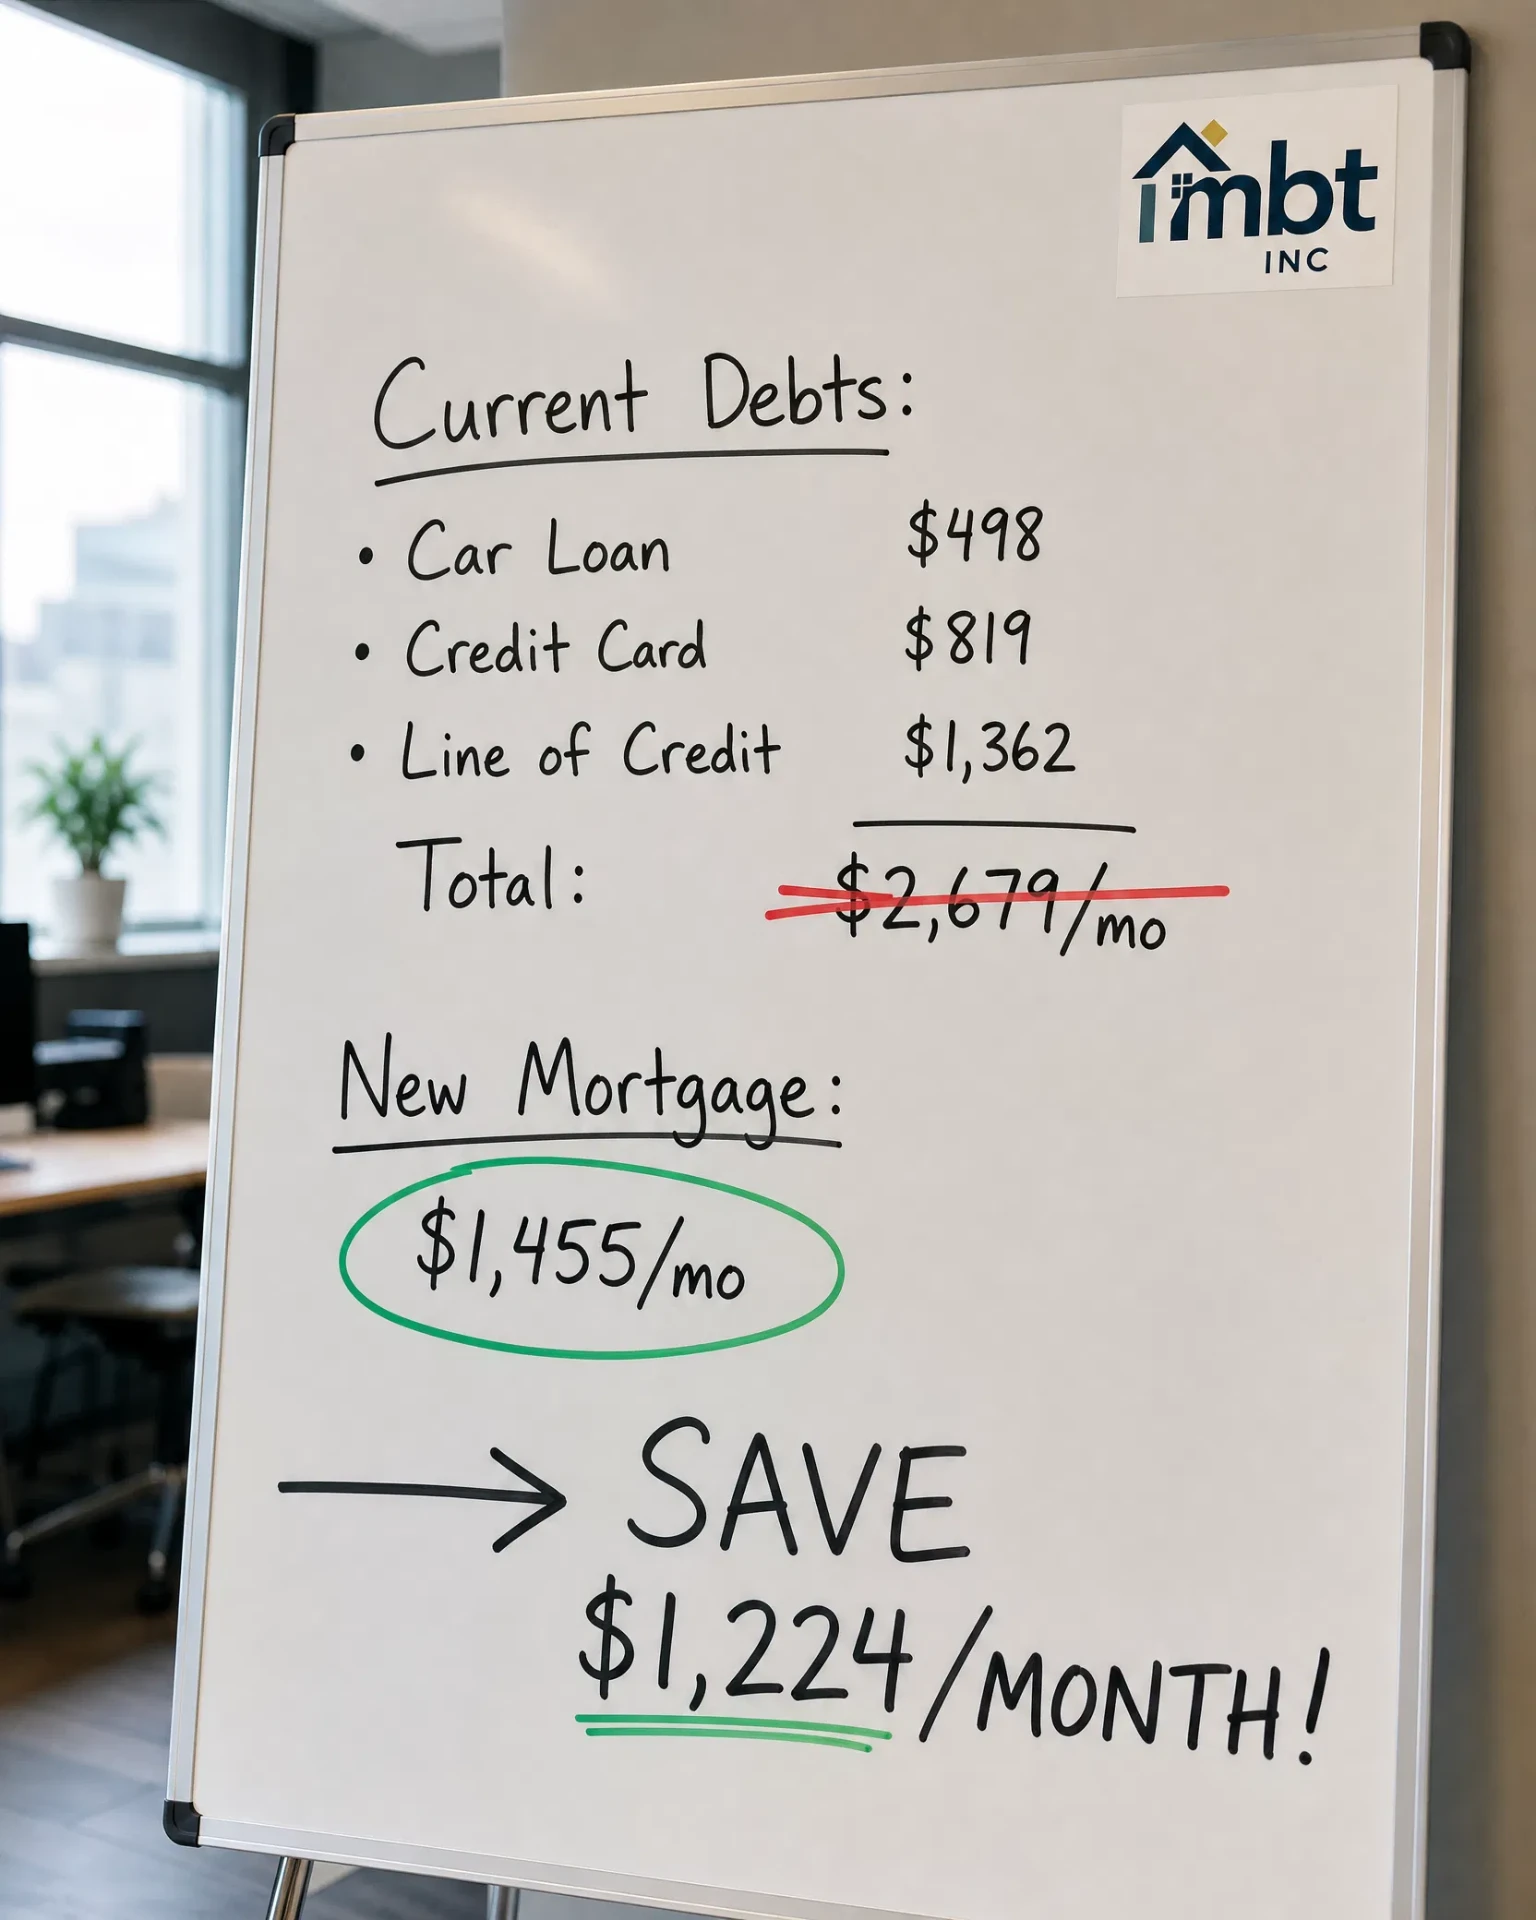
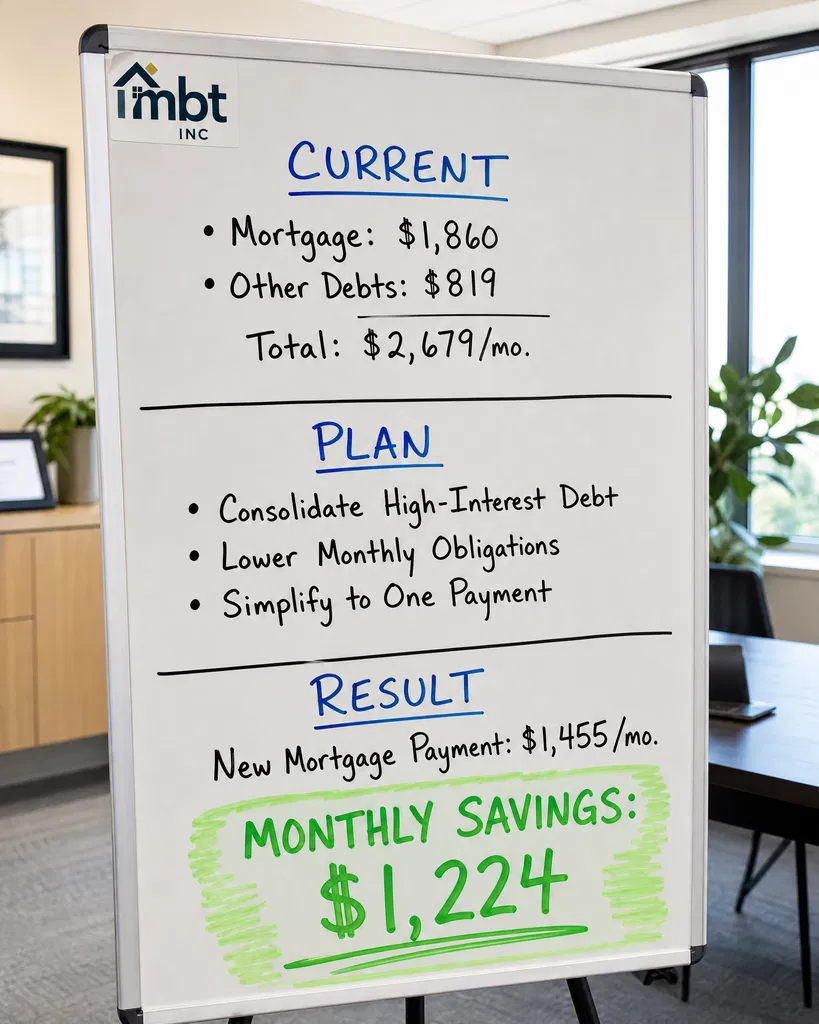
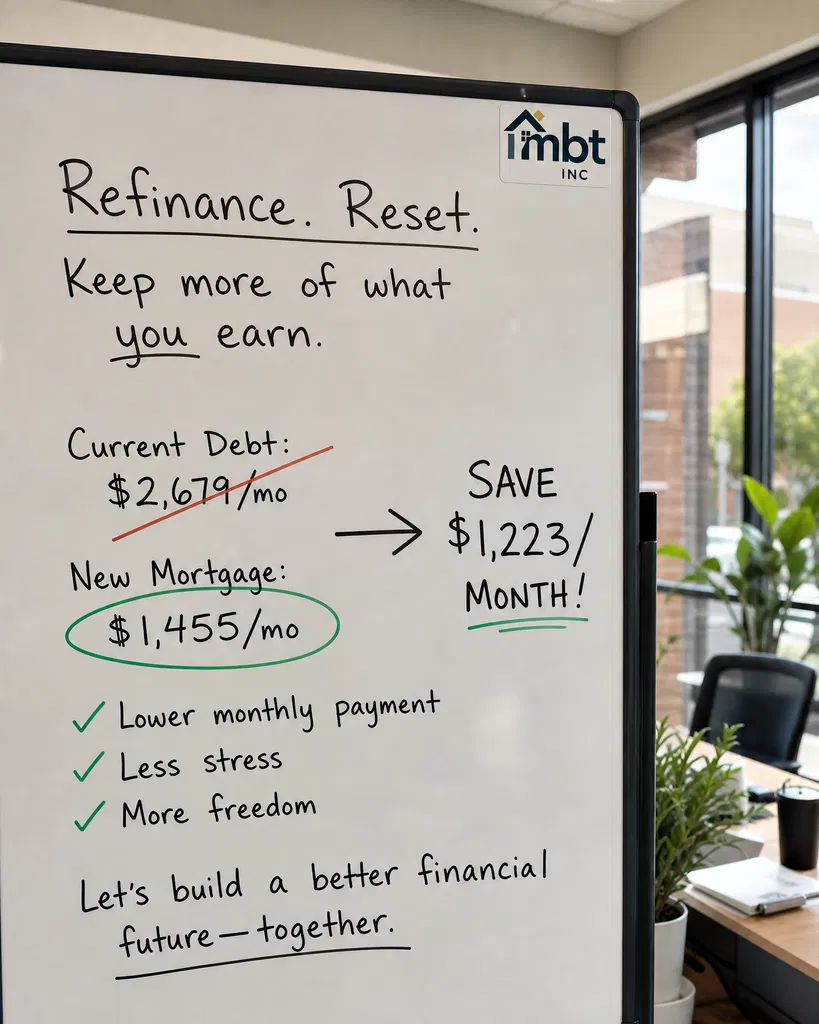
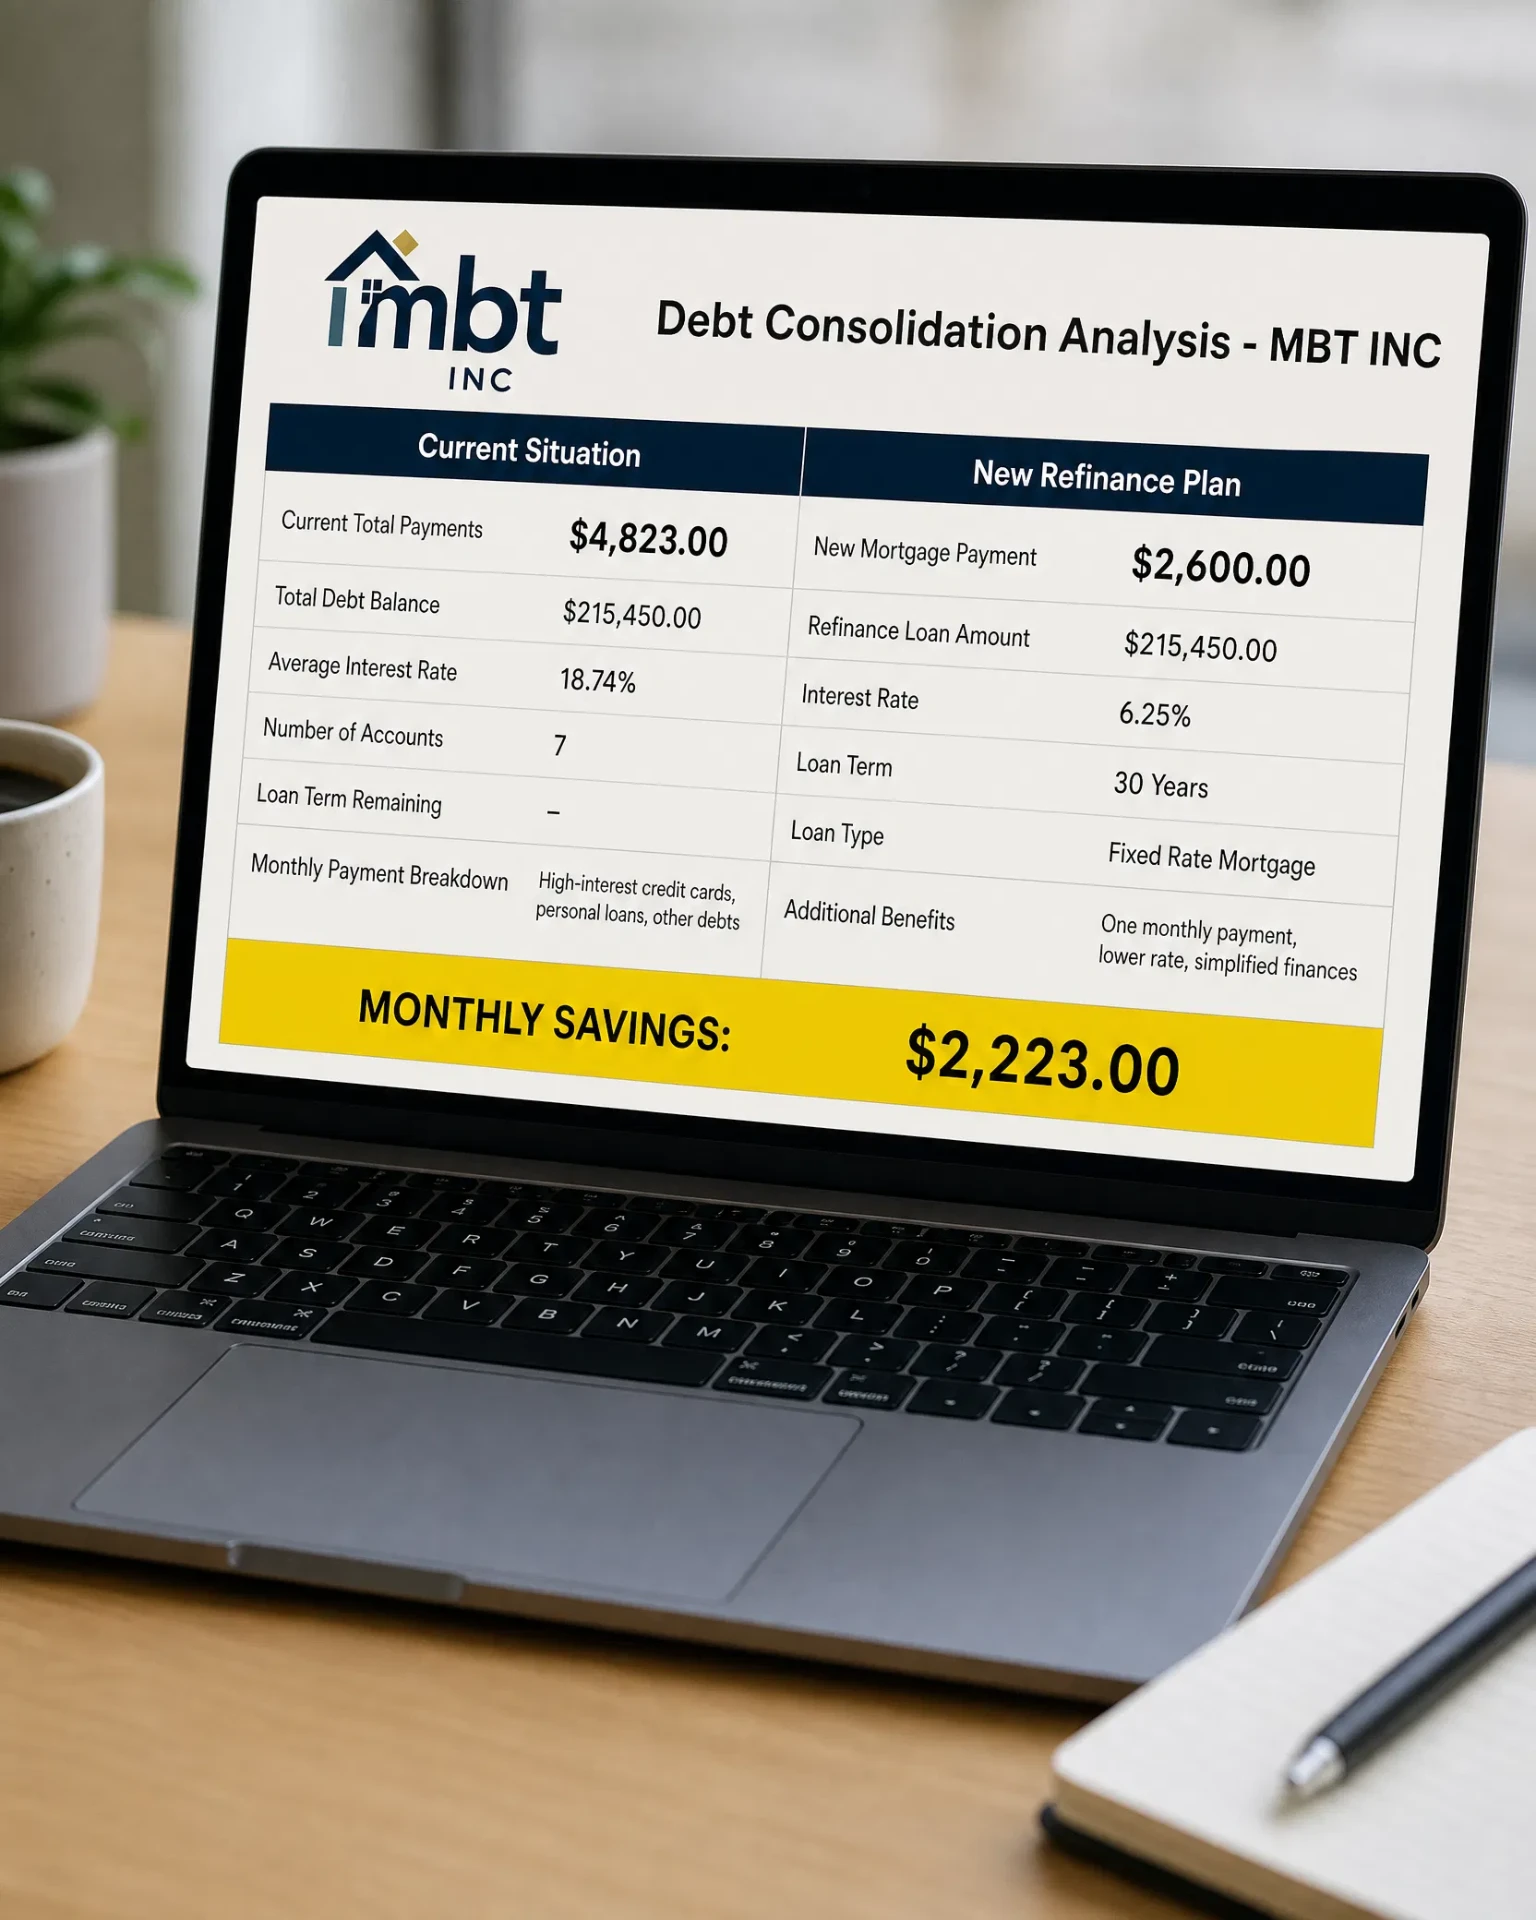
The whiteboard version of your mortgage
This is exactly how we work through it together: your real payments on one side, the new single payment on the other, and the monthly difference circled.
Straight answers, licensed advice, and the trade-offs in writing
You're not being sold a rate. You're being shown what your options actually cost you — monthly and over the life of the mortgage.
Licensed, and specialised
Led by Tiffany Quaye of Pineapple Financial Inc. — refinancing, debt consolidation and cash flow are the work, not a side line.
Both numbers, always
The monthly change and the total interest change. One without the other isn't advice.
Doing nothing counts as an option
If your penalty outweighs the benefit, that's what we'll tell you — and exactly why.
Complicated files welcome
Self-employed, commission, bruised credit, separations. Complicated is normal here.
No cost to you on most files
On standard residential mortgages the lender pays us. Any fee scenario is disclosed in writing first.
A real reply, quickly
Personal reply within one business day — from us, not a call centre.
I shop your mortgage across 30+ lenders — banks, monolines and private
One application, compared across lenders. You are not stuck with your bank's answer.
What working with us is like
Real client feedback, plus the credentials behind the advice.
“I am so pleased that I answered a FB ad to get an LOC. Tiffany is very professional and easy to work with. She knows what she is doing and was able to get funding ASAP. Thank you Tiffany.”
Licensed mortgage broker
Tiffany Quaye, brokering through Pineapple Financial Inc.
11+ years in mortgages
Refinancing, debt consolidation and cash-flow restructuring.
No cost to you
Lender-paid on most residential mortgages — you pay nothing for advice.
Straight answers, fast
A personal reply within one business day, every time.
Understand it before you sign it
Plain-language guides on refinancing, consolidating debt and Canadian mortgage rules.
Should I Refinance My Mortgage to Pay Off Debt?
Refinancing to pay off debt usually makes sense when the interest rate gap is large, you have equity below the 80% ceiling, and you have a p…
Read the guideDebtIs Debt Consolidation a Good Idea?
Debt consolidation is a good idea when it lowers your interest cost, reduces the risk of missed payments, and comes with a plan for the mone…
Read the guideRefinancingHow Much Equity Can I Take Out of My Home in Canada?
Most Canadian lenders allow you to borrow up to 80% of your home's appraised value. Subtract your existing mortgage balance from that figure…
Read the guideThe things people ask first
Short, honest answers — no rate bait, no fine print games.
What does a mortgage refinance actually do?
It replaces your existing mortgage with a new one — often larger — so you can access equity, consolidate debt, change your amortization or move to a better structure. In Canada you can generally refinance up to 80% of your home's appraised value.
Can refinancing lower my monthly payments?
It can, especially when high-interest debt is folded into the mortgage or the amortization is reset. The trade-off is that spreading debt over more years can increase the total interest you pay, which is why we model both numbers before deciding.
What's the difference between a HELOC and a refinance?
A refinance replaces your mortgage with a new one at today's terms. A home equity line of credit sits alongside or within your mortgage and lets you draw only what you need, paying interest on the drawn balance. Which one fits depends on your penalty, your equity and how you plan to use the funds.
Do I need perfect credit to refinance?
No. Equity and income matter alongside credit. Bruised credit changes which lenders make sense, not whether options exist.
Will this cost me anything to explore?
No. The initial conversation is free and involves no credit check. On standard residential files with prime lenders, the lender compensates us — any fee scenario is disclosed in writing before you commit.
Bring your numbers. We'll show you what's realistic.
Your mortgage balance, the balances you're carrying, and what's stressing you out is enough for us to come back with something useful. No credit check, no obligation, no pressure.
- Takes about two minutes on your phone
- No credit check, no SIN, no documents
- A real reply — personal reply within one business day
Prefer to talk? 416-649-6483 · tiffany@mortgagesbytiff.com
Licensed & regulated
Tiffany Quaye · Licensed Mortgage Agent
Brokerage: Pineapple Financial Inc.
Question 1 of 9
First things first — do you currently own a home?
This just tells me which options are even on the table.